

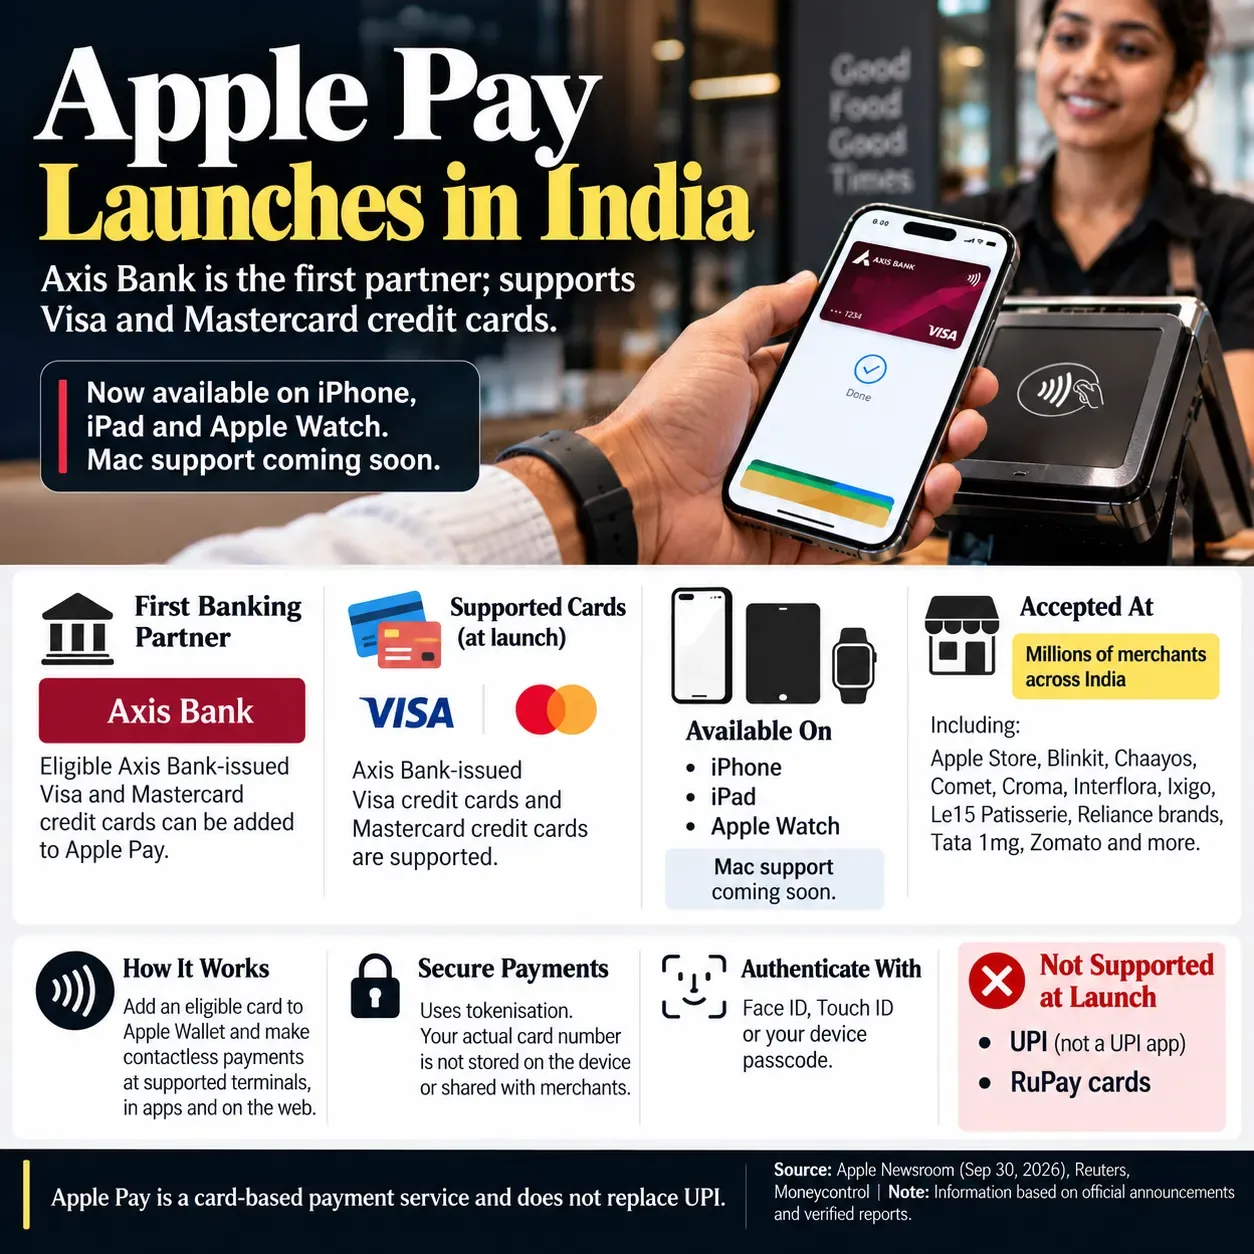
Apple Pay is now officially live in India. The service rolled out on September 30, 2026. It brings hardware-grade contactless payments to domestic iPhone users for the very first time.
The launch marks a major milestone. Yet, the rollout looks very different from what many expected. Apple did not build an open platform for all Indian banks. Instead, Apple partnered exclusively with Axis Bank.
Only eligible Visa and Mastercard credit cards work today. Debit cards are completely excluded. Domestic RuPay cards cannot be linked. Most importantly, Apple Pay is not a UPI app.
⚡ The Fast Facts: At a Glance
- Launch Date: September 30, 2026.
- Partner Bank: Axis Bank (Exclusive launch issuer).
- Supported Cards: Axis Bank Visa and Mastercard Credit Cards only.
- Unsupported Rails: Unified Payments Interface (UPI) and RuPay.
- Supported Devices: iPhone XR or later (iOS 18+) and Apple Watch Series 6 or later (watchOS 11+).
- Mac Support: Pending ("Coming Soon").
Why Is Apple Bypassing India’s UPI Ecosystem?
India is the undisputed world capital of real-time digital payments. The numbers prove it. A 2025 International Monetary Fund (IMF) study revealed a telling statistic. The Unified Payments Interface (UPI) commands roughly 84% of all digital payment volume in India.
So why did Apple ignore UPI? The answer lies in transaction economics and hardware philosophy.
UPI is a bank-to-bank instant messaging protocol. It links directly to savings accounts. National Payments Corporation of India (NPCI) enforces a zero Merchant Discount Rate (MDR) on standard consumer UPI transfers. In simple terms: nobody pays transaction fees.
Because there is no fee, there is no revenue margin. Apple cannot easily monetise zero-MDR transactions. Credit cards, however, tell a totally different story.
Credit cards carry commercial interchange fees. Merchants pay between 1.5% and 2.5% on credit card checkouts. Apple historically collects an estimated 0.15% cut on Apple Pay credit card volume globally. By prioritizing credit cards, Apple protects its financial services margins.
India Digital Volume Controlled by UPI
Indian Credit Card Spend (Annual 2025)
Targeting the Top Tier: India’s Spender Class
Apple is not chasing micro-payments. It is not competing with roadside tea stalls.
The Reserve Bank of India (RBI) tracks card payment statistics closely. In 2021, total annual credit card spends stood at ₹8.9 lakh crore. By 2025, that figure ballooned to ₹23.2 lakh crore across 570 crore transactions.
That is an explosion in card-based consumer debt. More importantly, credit card spends reflect high average order values. While a standard UPI payment averages around ₹1,200, an urban credit card swipe frequently exceeds ₹3,500.
iPhone owners in India match this exact demographic. They have disposable income. They carry multiple premium cards. They travel abroad frequently. Apple designed this rollout specifically for them.
How Apple Pay Works: Network Tokenisation Explained
Many consumers fear mobile card storage. Is Apple Pay truly safe? The short answer is yes.
Apple Pay does not store your plastic card number. It never saves your 16-digit card digits on your iPhone. It never uploads them to Apple servers. Merchants never see your real card details.
The system operates entirely on Network Tokenisation. This framework complies strictly with RBI security guidelines.
Here is what happens during a transaction:
- The Onboarding Token: You scan your Axis Bank card into Apple Wallet. Axis Bank, Visa, and Mastercard verify your identity.
- The Device Account Number: The network issues an encrypted mathematical token. This token is unique to your specific device.
- The Secure Element: Apple writes this token into an isolated physical chip inside your iPhone. This chip is called the Secure Element. It is air-gapped from iOS.
- The Tap: You double-click the side power button. You authenticate with Face ID. You hold your iPhone near an NFC reader.
- The Dynamic Cryptogram: The chip transmits the token alongside a one-time cryptographic code. That code cannot be reused.
Even if a rogue merchant skims the signal, the data is completely useless. There is no permanent number to steal. If your iPhone gets lost, you do not need to cancel your physical card. You simply freeze the digital token using the Find My app.
Technical Breakdown: Apple Pay vs UPI vs Physical Cards
To understand where Apple Pay fits, let us compare the three dominant transaction methods side by side:
| Feature | Apple Pay (India) | Standard UPI | Physical Credit Card |
|---|---|---|---|
| Payment Rail | Visa / Mastercard Card Rails | NPCI IMPS / Account Rails | Card Issuer Magnetic / EMV Chip |
| Authentication | Biometric (Face ID / Touch ID) | 4 or 6-digit Manual PIN | Physical PIN / No PIN under ₹5,000 |
| Card Data Sharing | Zero (Hardware Tokenised) | Virtual Payment Address (VPA) | 16 digits printed on plastic |
| Offline Tap Speed | Instant (< 1 second) | Requires Camera Scan & Network | Fast (1–2 seconds) |
| Current Bank Reach | Axis Bank Credit Cards Only | All Indian Commercial Banks | All Card Issuing Banks |
Hardware Compatibility: Which Devices Qualify?
Do not assume every iPhone works with the new service. Apple has enforced strict hardware and operating system minimums:
- iPhone: You need an iPhone XR or newer. The device must run iOS 18 or later. Older models like the iPhone 8 or iPhone X are unsupported.
- Apple Watch: Supported starting with Apple Watch Series 6 or newer. The watch must run watchOS 11 or later. It must remain paired to an iPhone XR or newer.
- iPad: Supported strictly for in-app and Safari web checkouts. You cannot tap an iPad against a physical retail POS terminal.
- Mac: Mac support is not available at launch. Apple explicitly confirms Mac integration is coming soon.
These requirements fit Apple’s broader device refresh cycle. Apple continues to update its modern premium iPhone lineup in India to support deeper cryptographic features.
The Merchant Network: Millions of POS Terminals Active
Did Apple install new payment machines across India? No. That would cost billions and take a decade.
Instead, Apple partnered with India’s leading payment infrastructure companies. Launch aggregators include Pine Labs, Razorpay, BillDesk, Cashfree, Juspay, PayU, Mswipe, Paytm, and Worldline.
Because of these aggregator partnerships, Apple Pay works immediately at any retail POS machine that supports contactless NFC payments. Major launch brands include official Apple Stores, Blinkit, Zomato, Tata 1mg, Reliance retail chains, Croma, Chaayos, Comet, Interflora, Ixigo, and Le15 Patisserie.
Visual Walkthrough: Card Tokenisation and Terminal Acceptance
The onboarding experience inside Apple Wallet is clean and straightforward. Below are the official deployment layouts for domestic users:

Notice the absence of manual CVV entries during checkout. The card interface relies entirely on the Device Account Number. This provides an impenetrable security layer during daily retail swipes.
The News4Bharat Perspective: The Real Reason HDFC and ICICI Are Missing
Why is Axis Bank standing alone on the launch stage? What happened to HDFC Bank and ICICI Bank?
Axis Bank is a formidable player. The bank managed 16.29 million active credit cards as of August 2026. That gives Apple access to roughly 13% of India's 124 million credit cardholders. But HDFC Bank and ICICI Bank together command over 40 million cards.
Reuters confirmed that Apple held extensive negotiations with both HDFC and ICICI. Yet, both banking giants refused to sign before launch day.
Our analysis indicates two massive stumbling blocks:
- The Commercial MDR Dispute: Global reports suggest Apple demands a share of the interchange fee on every swipe. Indian private banks operate on razor-thin margins. Tier-1 banks pushed back hard against giving up basis points to Apple.
- Customer Data Ownership: Indian banks guard customer relationship metadata fiercely. Apple’s privacy model obscures transaction data from external analytics. HDFC and ICICI rely on transaction histories to cross-sell personal loans, mutual funds, and mortgages.
Axis Bank took a calculated risk. By agreeing to Apple's terms, Axis Bank secured a temporary monopoly. For the next few months, any wealthy Indian iPhone owner wanting Apple Pay must swipe an Axis Bank credit card. That is an enormous customer acquisition magnet.
What This Means for the Future of Indian Fintech
Apple Pay will not kill UPI. It was never designed to do so.
UPI remains the backbone of Indian commerce. It moves money for billions of everyday transactions. But Apple Pay creates a fortress around premium card transactions. It eliminates physical wallets for high-income earners.
The absence of RuPay remains Apple's biggest strategic vulnerability. NPCI has rapidly expanded RuPay credit cards linked directly to UPI. If Apple wants universal adoption across Bharat, it must eventually build a bridge to NPCI rails.
For now, the battle lines are clear. Apple has planted its flag in Indian soil. It picked a high-value entry point. Watch subsequent exchange filings closely as rival private banks reconsider their commercial terms.
This is a developing financial story. Follow News4Bharat for upcoming regulatory filings from the Reserve Bank of India, NPCI updates, and issuer onboarding announcements.
Frequently Asked Questions (FAQ)
Clear, verified answers to the most common questions regarding Apple Pay's launch in India.
Can I link my Google Pay or PhonePe UPI account to Apple Pay?
No. Apple Pay does not integrate with UPI. It is strictly a card tokenisation service for supported credit cards.
Which cards work with Apple Pay in India right now?
Only eligible Axis Bank-issued Visa and Mastercard credit cards work at launch. Debit cards and RuPay cards are unsupported.
Does Apple Pay work on Apple Watch without an iPhone nearby?
Yes. The Apple Watch stores its own encrypted token in its Secure Element. You can tap and pay without carrying your iPhone.
Do I have to pay extra fees to use Apple Pay?
No. Apple does not charge consumers any additional fee for transactions. Standard card charges and merchant terms apply.
When will HDFC Bank, ICICI Bank, and SBI support Apple Pay?
No official date has been confirmed. Reuters reports commercial negotiations remain ongoing between Apple and other Tier-1 Indian lenders.