

Global tech investor Prosus is making a massive move in India.
The Amsterdam-listed giant is rapidly expanding its footprint in financial technology. Right now, Prosus is in active talks to fund two major platforms: Kiwi and Oolka.
These are not small checks. They represent a major strategic shift. Prosus is moving past simple payment processing. It is diving deep into consumer credit, UPI loans, and artificial intelligence.
Crucial Fact Check
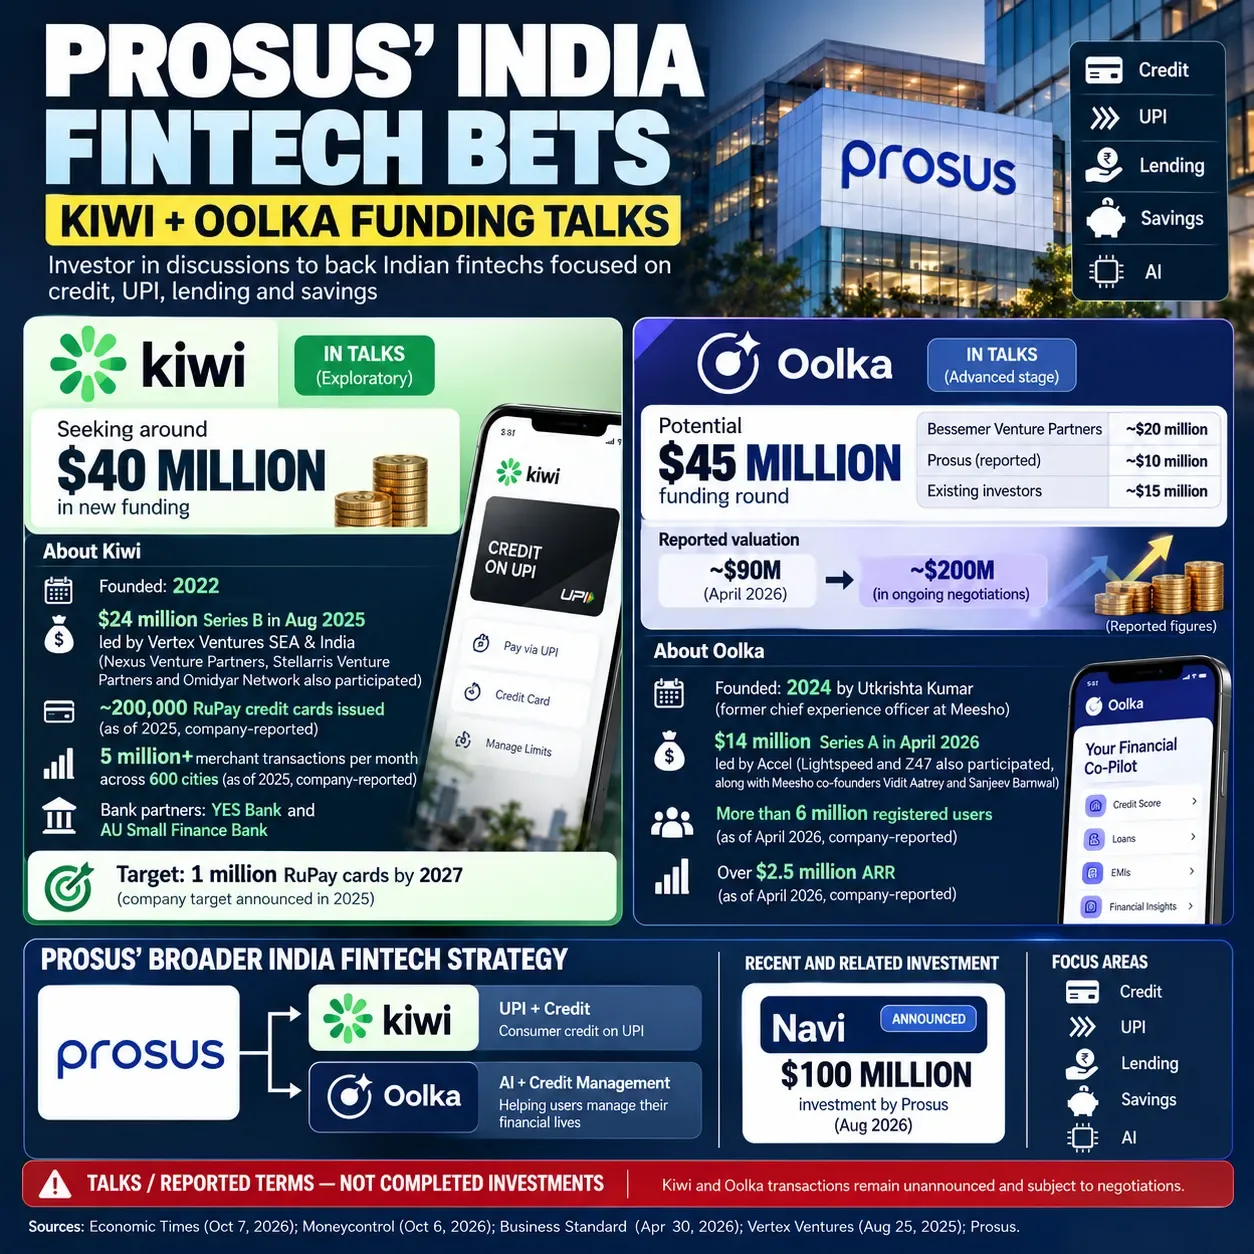
Neither transaction is a completed deal today. Kiwi is in exploratory talks to raise up to $40 million. Oolka is in advanced negotiations for a $45 million round.
The Deals at a Glance
What exactly is happening behind closed doors? Here is the breakdown of the potential investments.
| Startup | Business Model | Target Fundraise | Current Status |
|---|---|---|---|
| Kiwi | Credit on UPI & RuPay | $30M – $40M | Exploratory discussions |
| Oolka | AI Credit Management | ~$45M | Advanced negotiations |
Kiwi's Backstory: In August 2025, Kiwi raised a $24 million Series B. Vertex Ventures led that round. Today, Kiwi manages over 200,000 RuPay credit cards. They partner heavily with YES Bank and AU Small Finance Bank.
Oolka's Backstory: Oolka moves fast. They just closed a $14 million Series A in April 2026. Accel led that deal. Now, they are discussing a $45 million round. Bessemer Venture Partners may invest $20 million. Prosus may add $10 million. Existing investors would cover the rest.
Why is Prosus Betting on "Credit on UPI"?
UPI changed how India pays. Now, it is changing how India borrows.
For years, the Unified Payments Interface (UPI) was strictly a debit system. You scanned a code, and the money left your bank account instantly. You had to have cash to spend cash.
The Reserve Bank of India (RBI) recently changed the rules. They allowed RuPay credit cards to link directly to UPI.
How Kiwi Capitalizes on This Shift
- No Plastic Cards: Kiwi issues virtual RuPay cards instantly.
- Zero Hardware Needed: Merchants do not need bulky swiping machines. They just use their existing QR codes.
- Massive Reach: Kiwi brings the power of a credit card to millions of local corner shops.
Founded in 2022, Kiwi built its entire business around this shift. This is why Prosus is interested. Kiwi is turning India's largest payment network into a massive credit distribution machine.
The AI Financial Agent: What is Oolka?
Oolka operates in the hottest sector of 2026: Artificial Intelligence in Finance.
Utkrishta Kumar, a former executive at Meesho, founded Oolka in 2024. Oolka acts like a highly intelligent, automated financial advisor in your pocket.
The app uses AI agents to track your credit score, monitor your EMI schedules, and suggest better loan options. It actively helps consumers manage their debt.
Crucial Distinction: Oolka is NOT a Bank.
Oolka's official disclosures make this very clear. They do not lend their own money. They act as a technology matchmaker. Regulated banks and NBFCs issue the actual loans. Oolka simply provides the smart software to discover and manage those loans.
The "Full-Stack" Masterplan: Prosus Beyond PayU
For over ten years, when you thought of Prosus in India, you thought of PayU. PayU is massive, but it mainly processes merchant payments.
Processing payments is a tough business. Margins are razor-thin. To make real money in Indian fintech today, you must distribute credit.
Look at the recent moves made by Prosus. They are building a complete financial puzzle.
- 1. PayU: Handles the merchant checkout process.
- 2. Navi Technologies: Proposed $100M investment for massive balance-sheet lending.
- 3. Kiwi (In Talks): Controls the everyday UPI credit transactions.
- 4. Oolka (In Talks): Owns the intelligent customer interface and credit advice.
This is a complete financial ecosystem. They are targeting the Indian consumer from every possible angle.
News4Bharat Perspective: The Compliance Challenge
Venture capital is eager to fund these platforms. However, the regulatory roadblocks are massive.
The RBI watches digital lending closely. Furthermore, India’s new Digital Personal Data Protection (DPDP) Act creates strict rules for AI platforms like Oolka.
AI fintech tools cannot just collect data freely. They must secure clear, auditable customer consent. They must prove their algorithms do not unfairly discriminate against borrowers. Scaling these platforms legally will cost millions in compliance infrastructure.
Editorial Closing
Prosus is sending a clear message to the market. Payment gateways alone are no longer enough.
The future of Indian fintech belongs to companies that can seamlessly combine UPI infrastructure with consumer lending and AI guidance. Investors must now watch closely. Will these negotiation talks successfully close? Follow subsequent corporate exchange filings to see if Prosus finalizes these massive capital deployments.