

The $7.3 Billion Financial Explosion: Unpacking India’s Q3 2026 BFSI Deal Surge
Did you know the Indian financial sector just witnessed one of its most dramatic cash injections in recent history?
It is absolutely true. The financial landscape is shifting beneath our feet.
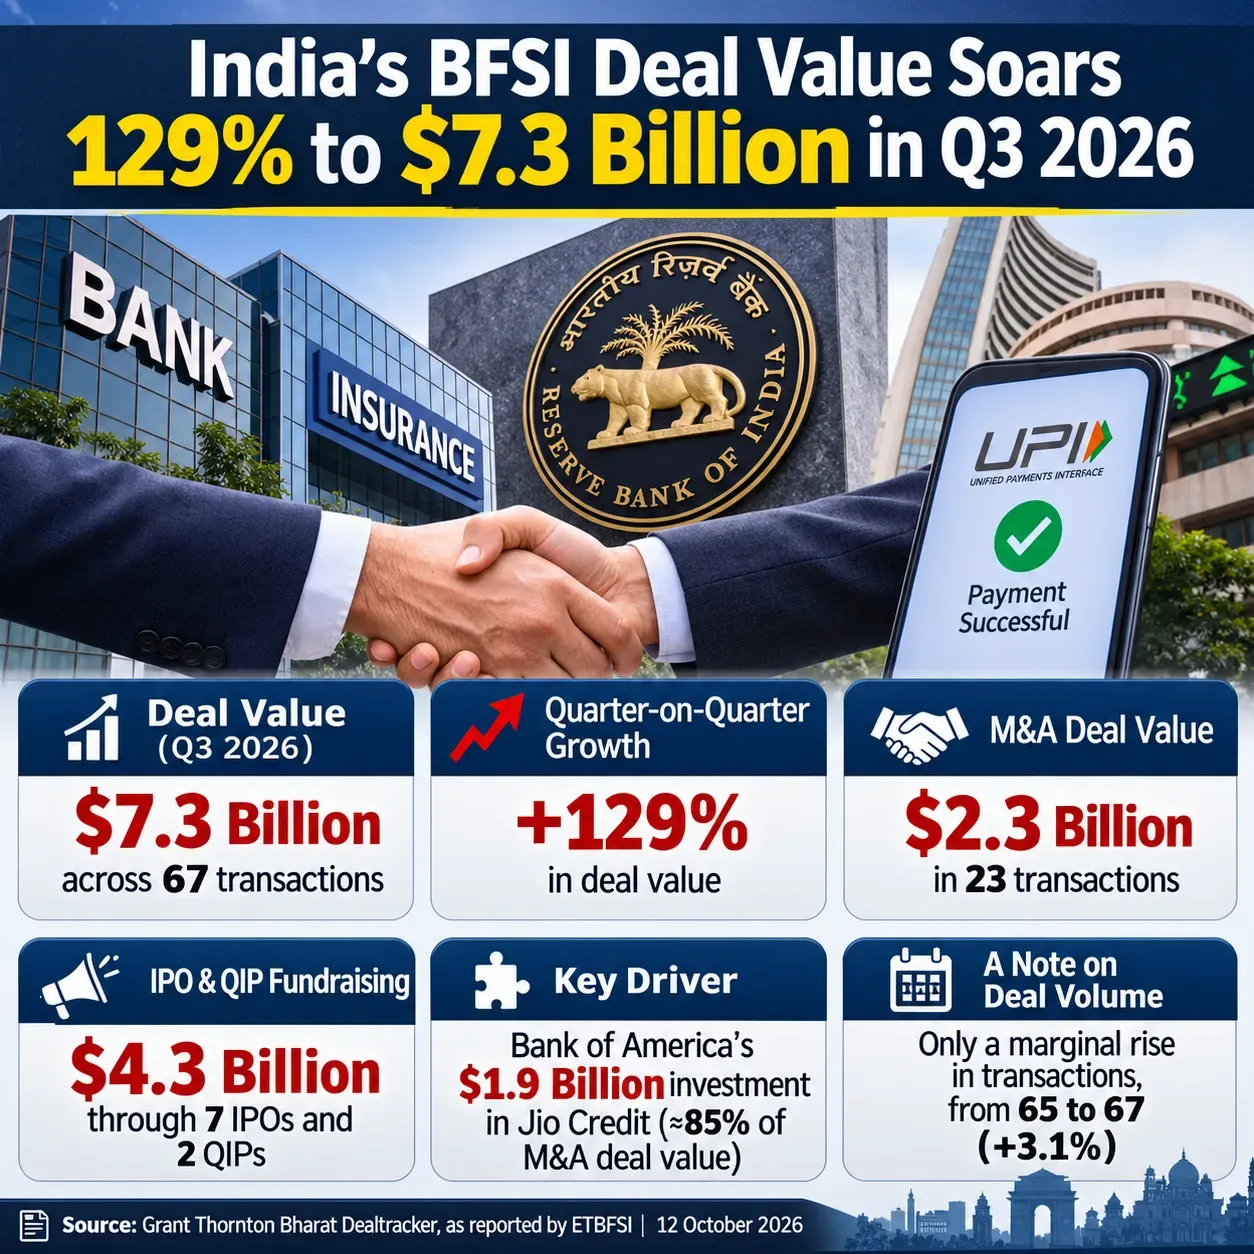
If you track the money, you track the future of the economy. And right now, the money is screaming a very specific message. The India BFSI deal value Q3 2026 reached an astonishing $7.3 billion. That is a massive number.
To put that in perspective, that represents a 129% jump compared to the previous quarter.
But wait. Before you assume that every startup and regional bank is swimming in cash, you need to look closer. The truth is much more complex—and much more fascinating.
Why You Need to Read This Explainer
This 2,000+ word deep dive breaks down the latest Grant Thornton Bharat Dealtracker report. We will uncover exactly where this money came from, who got it, and what it means for the future of your investments, your business, and India's economy.
Let's dive into the data.
1. The Great Illusion: Value vs. Volume
Here is a pattern interrupt that might surprise you: Deal volume barely moved.
While the total amount of money surged by 129%, the actual number of deals only increased from 65 to 67. That is a microscopic 3.1% rise in transaction count.
What does this mean in plain English?
It means the wealth was not spread evenly. A massive tide of capital came in, but it only lifted a few very large, very specific boats. The broader market—the smaller players, the early-stage startups—did not see a massive windfall.
- Total Deal Value: $7.3 Billion (Up 129%)
- Total Deal Volume: 67 Transactions (Up only 3.1%)
- The Reality Check: Compared to exactly one year ago (Q3 2025), deal value is actually down 5%, even though volume is up 10%.
This gap between volume and value is the most crucial takeaway for any financial professional. An increase in total value driven by just a few transactions reflects a limited set of strategic power plays. It does not reflect a booming, easy-money market for everyone.
2. The $1.9 Billion Elephant in the Room: Bank of America and Jio Credit
You cannot understand the India BFSI deal value Q3 2026 without looking at one specific, monumental transaction.
Mergers and acquisitions (M&A) hit $2.3 billion for the quarter. But there is a catch. A staggering 85% of that entire value came from just one deal.
Bank of America Corporation has proposed a mammoth $1.9 billion (approximately ₹18,268 crore) investment in Jio Credit Limited.
The Deal Structure Simply Explained: Bank of America aims to acquire up to a 49.9% interest in Jio Credit. They are doing this through a "preferential allotment" of equity shares and warrants. This means new shares are created specifically for Bank of America, injecting fresh capital directly into the company's lending engine.
Why is this transaction so critical to the Indian financial ecosystem?
The Logic for Jio Financial Services
Jio Credit is the lending arm of Jio Financial Services. Lending requires immense capital. To lend more money to millions of Indians, you need a massive war chest. Jio Credit already boasted assets under management (AUM) of ₹30,667 crore as of mid-2026. This $1.9 billion injection acts as rocket fuel.
But it is not just about the money. Jio gets Bank of America's elite global expertise. They get world-class risk management, stringent governance models, and advanced financial technology frameworks.
The Logic for Bank of America
Foreign banks have historically struggled to build large-scale retail lending operations in India from scratch. It is expensive, highly regulated, and incredibly competitive. By buying into Jio Credit, Bank of America skips the line.
They gain instant access to Jio's unparalleled domestic digital reach and local market knowledge. It is a strategic masterstroke: partner with a local giant rather than fighting them.
However, a word of caution: Without this single deal, the M&A market in Q3 2026 would look incredibly weak. Domestic M&A transactions made up 78% of the volume, but only 9% of the value. The big money is inbound, and it is highly concentrated.
3. Public Markets on Fire: The IPO and QIP Explosion
If the M&A market was dominated by one deal, the public markets were dominated by two.
Public-market fundraising was the second massive driver of the Q3 surge. Companies successfully raised approximately $4.3 billion through the public markets.
How did they do it?
- Initial Public Offerings (IPOs): Seven companies went public.
- Qualified Institutional Placements (QIPs): Two listed companies raised fresh funds.
This is a massive leap from Q2, which saw only one IPO and two QIPs. But again, the theme of concentration appears. Out of that $4.3 billion, almost all of it came from two legacy giants.
The Blockbuster Offerings
National Stock Exchange (NSE) IPO: ~$2.4 Billion
SBI Funds Management IPO: ~$1.0 Billion
Together, the NSE and SBI Funds Management offerings accounted for roughly 84% of the value in the financial services and asset management segment.
What does this tell us?
It tells us that retail and institutional investors have a massive appetite for established, trusted financial franchises. They are willing to write huge checks for businesses with proven monopolies (like NSE) or massive distribution networks (like SBI Funds Management).
But there is a warning sign here too. Total public-market fundraising actually declined by about 16% year-on-year, even though the number of issuances increased by 50%. More companies are going to the market, but the total pie of capital is slightly shrinking compared to last year.
4. The Private Equity Paradox: Why Did VC Funding Crash 44%?
Here is the most striking pattern interrupt in the entire Q3 data set.
While M&A and public markets soared, Private Equity (PE) and Venture Capital (VC) activity took a severe hit.
In Q3 2026, PE/VC recorded 35 transactions. The aggregate value? A modest $736 million.
Compared to the previous quarter, transaction volume dropped 8%. But the total value plummeted by an alarming 44%.
Why are private investors suddenly so shy?
It comes down to three main factors:
- Valuation Mismatches: Founders still want 2021-era valuations. Investors, facing higher global interest rates, are demanding realistic, revenue-backed valuations. The two sides are struggling to agree.
- The Profitability Mandate: Gone are the days of funding "growth at all costs." VC firms are demanding clear, proven routes to profitability. If a startup is burning cash without a clear timeline to break even, the funding gets cut.
- Smaller Tactical Bets: Investors are spreading their risk. A staggering 91% of PE/VC transactions by volume were below $50 million. They are making smaller, more tactical bets rather than writing massive $200 million checks.
The Silver Lining: Notable PE Investments
Despite the slowdown, strong companies still raised capital. The largest reported PE investments included:
- NIIF Infrastructure Finance: ~$182 million
- Slice: ~$100 million
- Navi Technologies: ~$100 million
The PE/VC slowdown does not mean investors are abandoning India. It means they are becoming highly disciplined. For fintech startups, the message is clear: show us the unit economics, or we walk away.

5. The Tale of Two Sectors: Fintech vs. NBFCs
If you want to understand where the India BFSI deal value Q3 2026 is actually flowing, you have to compare Fintech with NBFCs (Non-Banking Financial Companies).
The data reveals a fascinating split personality in the market.
Fintech: High Volume, Shrinking Value
Fintech remains the most popular kid in school. It recorded 30 transactions, making up 45% of total deal activity by volume. The transaction count was actually up 11% year-on-year.
But...
The deal value was only $722 million. That is a brutal 52% drop compared to the previous quarter. Fintech is seeing lots of activity, but the checks are getting much smaller. Seed and Series A rounds are happening, but late-stage mega-rounds have virtually vanished.
NBFCs: Low Volume, Exploding Value
Traditional banking and NBFCs told the exact opposite story.
They only recorded 15 transactions. But the value of those transactions? A mammoth $2.5 billion.
Deal value in this space rose nearly ninefold quarter-on-quarter. Of course, this was heavily skewed by the Jio Credit deal, the Piramal Finance QIP ($221 million), and the NIIF investment. Together, these three deals accounted for 93% of the NBFC segment's value.
The strategic takeaway: Hard lending businesses with actual balance sheets (NBFCs) are attracting massive strategic capital. Software and payment layers (Fintech) are seeing high activity but lower overall valuations.
6. What Does This Mean for the Everyday Investor?
Financial reports can feel incredibly abstract. Billions of dollars moving between massive corporations. But how does this $7.3 billion surge impact you?
Here is the trickle-down effect simplified:
- Better Lending Rates: Mega-deals like Jio Credit mean more capital is entering the lending system. When well-funded NBFCs compete for your business, it can lead to more accessible consumer loans and competitive interest rates for everyday borrowers.
- Retail IPO Opportunities: The success of the NSE and SBI Funds Management IPOs proves the market is healthy. This encourages other highly profitable, legacy companies to go public, giving retail investors a chance to buy into stable, dividend-paying businesses.
- Safer Fintech Apps: The drop in PE/VC funding forces fintech startups to mature. They cannot rely on endless VC cash to subsidize cashbacks or reckless lending. They must build sustainable, secure, and profitable platforms. Ultimately, this results in a safer ecosystem for the end-user.
News4Bharat POV: Looking Ahead to Q4 2026
The 129% jump in the India BFSI deal value Q3 2026 is a spectacular headline. It shows that global capital still deeply trusts the structural growth of India's financial ecosystem.
However, as elite financial professionals, we must separate the signal from the noise.
This is not a broad-based boom. It is a highly concentrated, top-heavy surge. Moving forward, here is exactly what we need to watch:
- Deal Execution: Will the Bank of America-Jio Credit deal clear all regulatory hurdles smoothly? A letter of intent is not a closed deal. We must watch the regulatory filings closely.
- The IPO Pipeline: Can the market sustain this level of public fundraising? The NSE and SBI sucked up a lot of liquidity. Will smaller financial companies find public buyers in Q4?
- Asset Quality is King: With NBFCs raising massive capital to lend, the next hurdle is credit quality. Throwing money at the market is easy; recovering it is hard. The real test of this $7.3 billion quarter will be the non-performing asset (NPA) numbers we see 12 to 18 months from now.
The Bottom Line
Capital is abundantly available in India, but the era of indiscriminate funding is definitively over. Today, the billions only flow toward proven monopolies, bulletproof unit economics, and strategic joint ventures.
Editorial Note: This explainer is based on the published Q3 2026 Dealtracker figures from Grant Thornton Bharat and cited company announcements. Deal values are approximate. Announced investments do not constitute executed transactions until independently confirmed by regulatory authorities.